US Battery Monthly
Overview
- US automakers and their focus on lower-cost battery systems to unlock mass-market platforms and
- Surging BESS storage demand as the new AI economy transforms US power balances
- Detailed insights on US battery demand, including monthly EV and ESS cell demand, including OEM/BESS-cell offtake deals
- Role of government policy on both a federal and state level and the implications for US cell manufacturers and midstream players.
- Monitoring US cathode balances and chemistry outlooks, including both traditional and next-generation technologies (e.g. sodium-ion)
- Developments in the US battery offtake market and the individual supply chains of both OEMs and cellmakers, particularly Korean producers.
2030 US Battery Value Chain
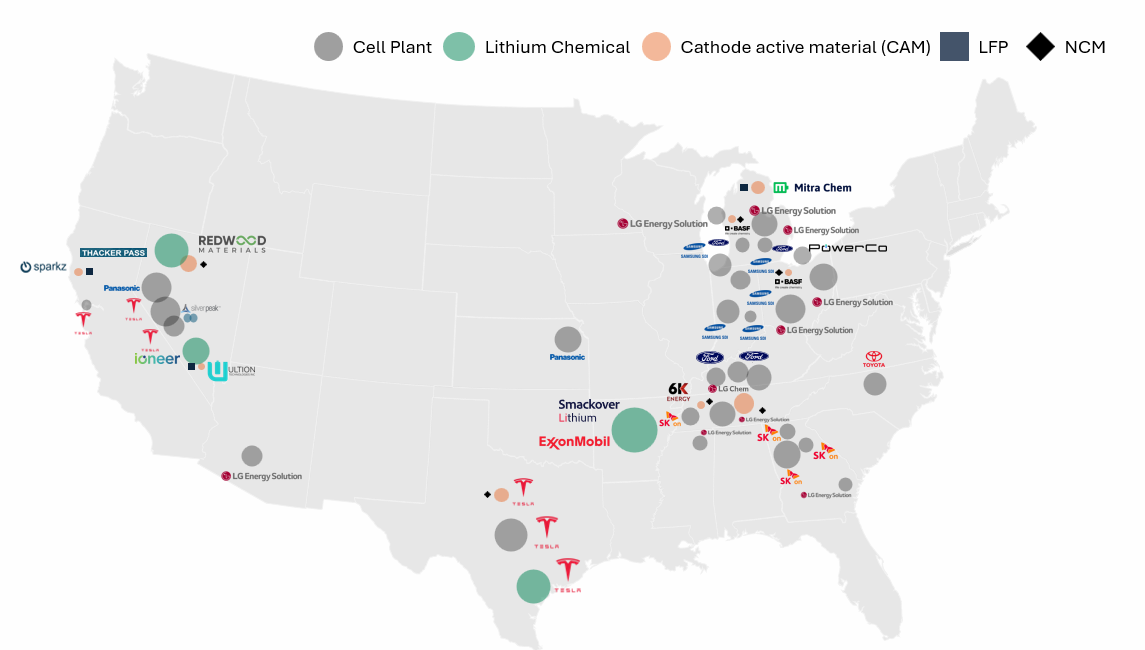
Source: REA
Note: Bubble size has been converted to Gwh across CAM, Cell and Li and is based on existing and planned capacity (2025)
Our Benefits
US cell balances
REA provides detailed coverage on US EV and ESS cell demand, supply by chemistry and company, utilisation rates and import trends
Supply Chain Strategy
REA provides granular detail on the supply chain strategies of US OEMs and cellmakers, including offtake details for cathode active materials and Li. REA also tracks 45X compliance and the impact of government policy on delivered cell costs and pricing.
Upstream
REA tracks developments in the US lithium market, focusing on US cost curve economics, DLE economics, offtake strategy and pricing developments.
Government strategy
REA regularly works with US government bodies on the impact of policy on US battery market outcomes, particularly the requirements for US midstream capacity building.
South Korean LiB producers set to dominate the US market
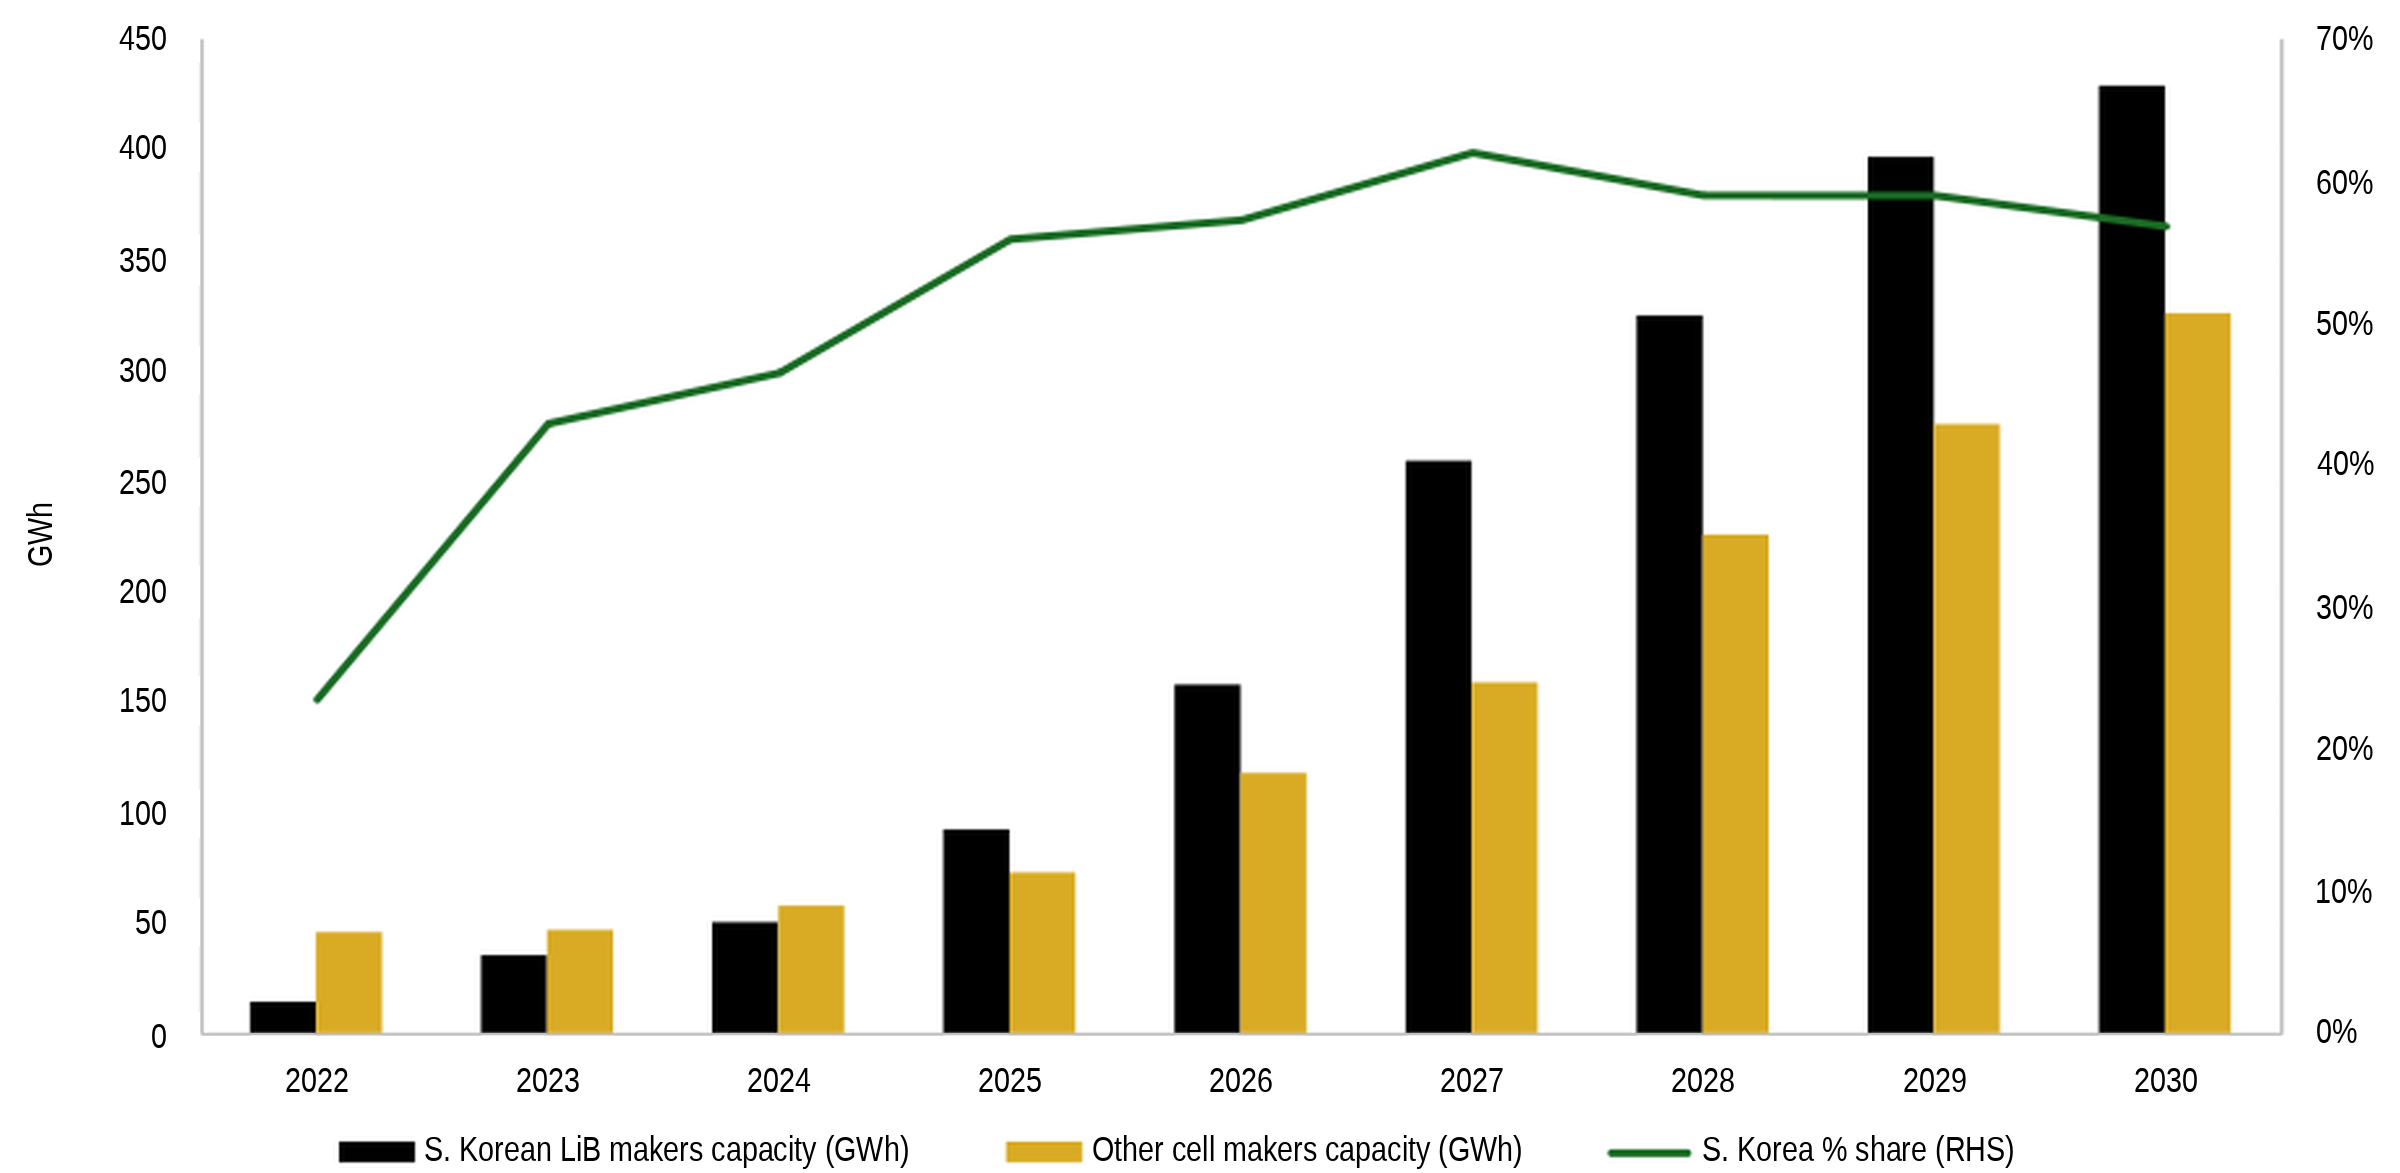
Korean players face intense competition outside the US