China Minimum Pricing
How will minimum pricing for Chinese EVs affect the EU market?
EU authorities have agreed in principle with the idea of introducing minimum pricing on BEVs imported from China. The decision, announced in mid-January, is set to reverse tariffs, ranging between about 18-45% depending on the OEM, that were introduced on Chinese-made BEVs in 2024. Under a minimum pricing system, OEMs intending to export to the EU will need to submit a price floor for each specific model and configuration. The EU will assess that suggested floor price with reference to the model’s cost and the implied duty that it would have faced under the tariff regime or by comparing a model directly to equivalents available domestically.
The intention is to mirror the impact that tariffs supposedly had on BEV export prices to the EU market, and to avoid the kind of race to the bottom in vehicle pricing that has played out in China over the last two years or so. At first glance the new system seems bureaucratic. It will involve the EU authorities monitoring BEV prices and potentially adjusting minimum price floors in response to design changes and variations in battery pack sizes, for example. Given Chinese OEMs are consistently launching new models, this is likely to be a significant undertaking.
In practice, the system also seems biased in favour of setting too high a minimum price floor. The baseline will be set with reference to import prices going back three years. As BEV technology and battery costs have declined over that period, use of some reference prices that are three-years’ old could return inflated results. In pricing terms, that would seem to benefit the OEMs. Instead of having to swallow some of the cost of tariffs—which Chinese OEMs have largely been doing since 2024—they will be able to fully internalise the higher margin that would come with a minimum floor price.
However, the impact on demand may not be so beneficial. By putting a floor—perhaps at too high a level—under BEV prices, there is risk that marginal demand growth will be restrained. One of the central lessons of recent years is that western OEMs have struggled to make BEVs suitable for the entry level or mass market segments of the passenger car market. A minimum pricing arrangement is unlikely to speed this process up in future. With tariffs in place, OEMs had the option to absorb some of the cost themselves, whereas now the logic will be to price to the minimum floor as a last resort.
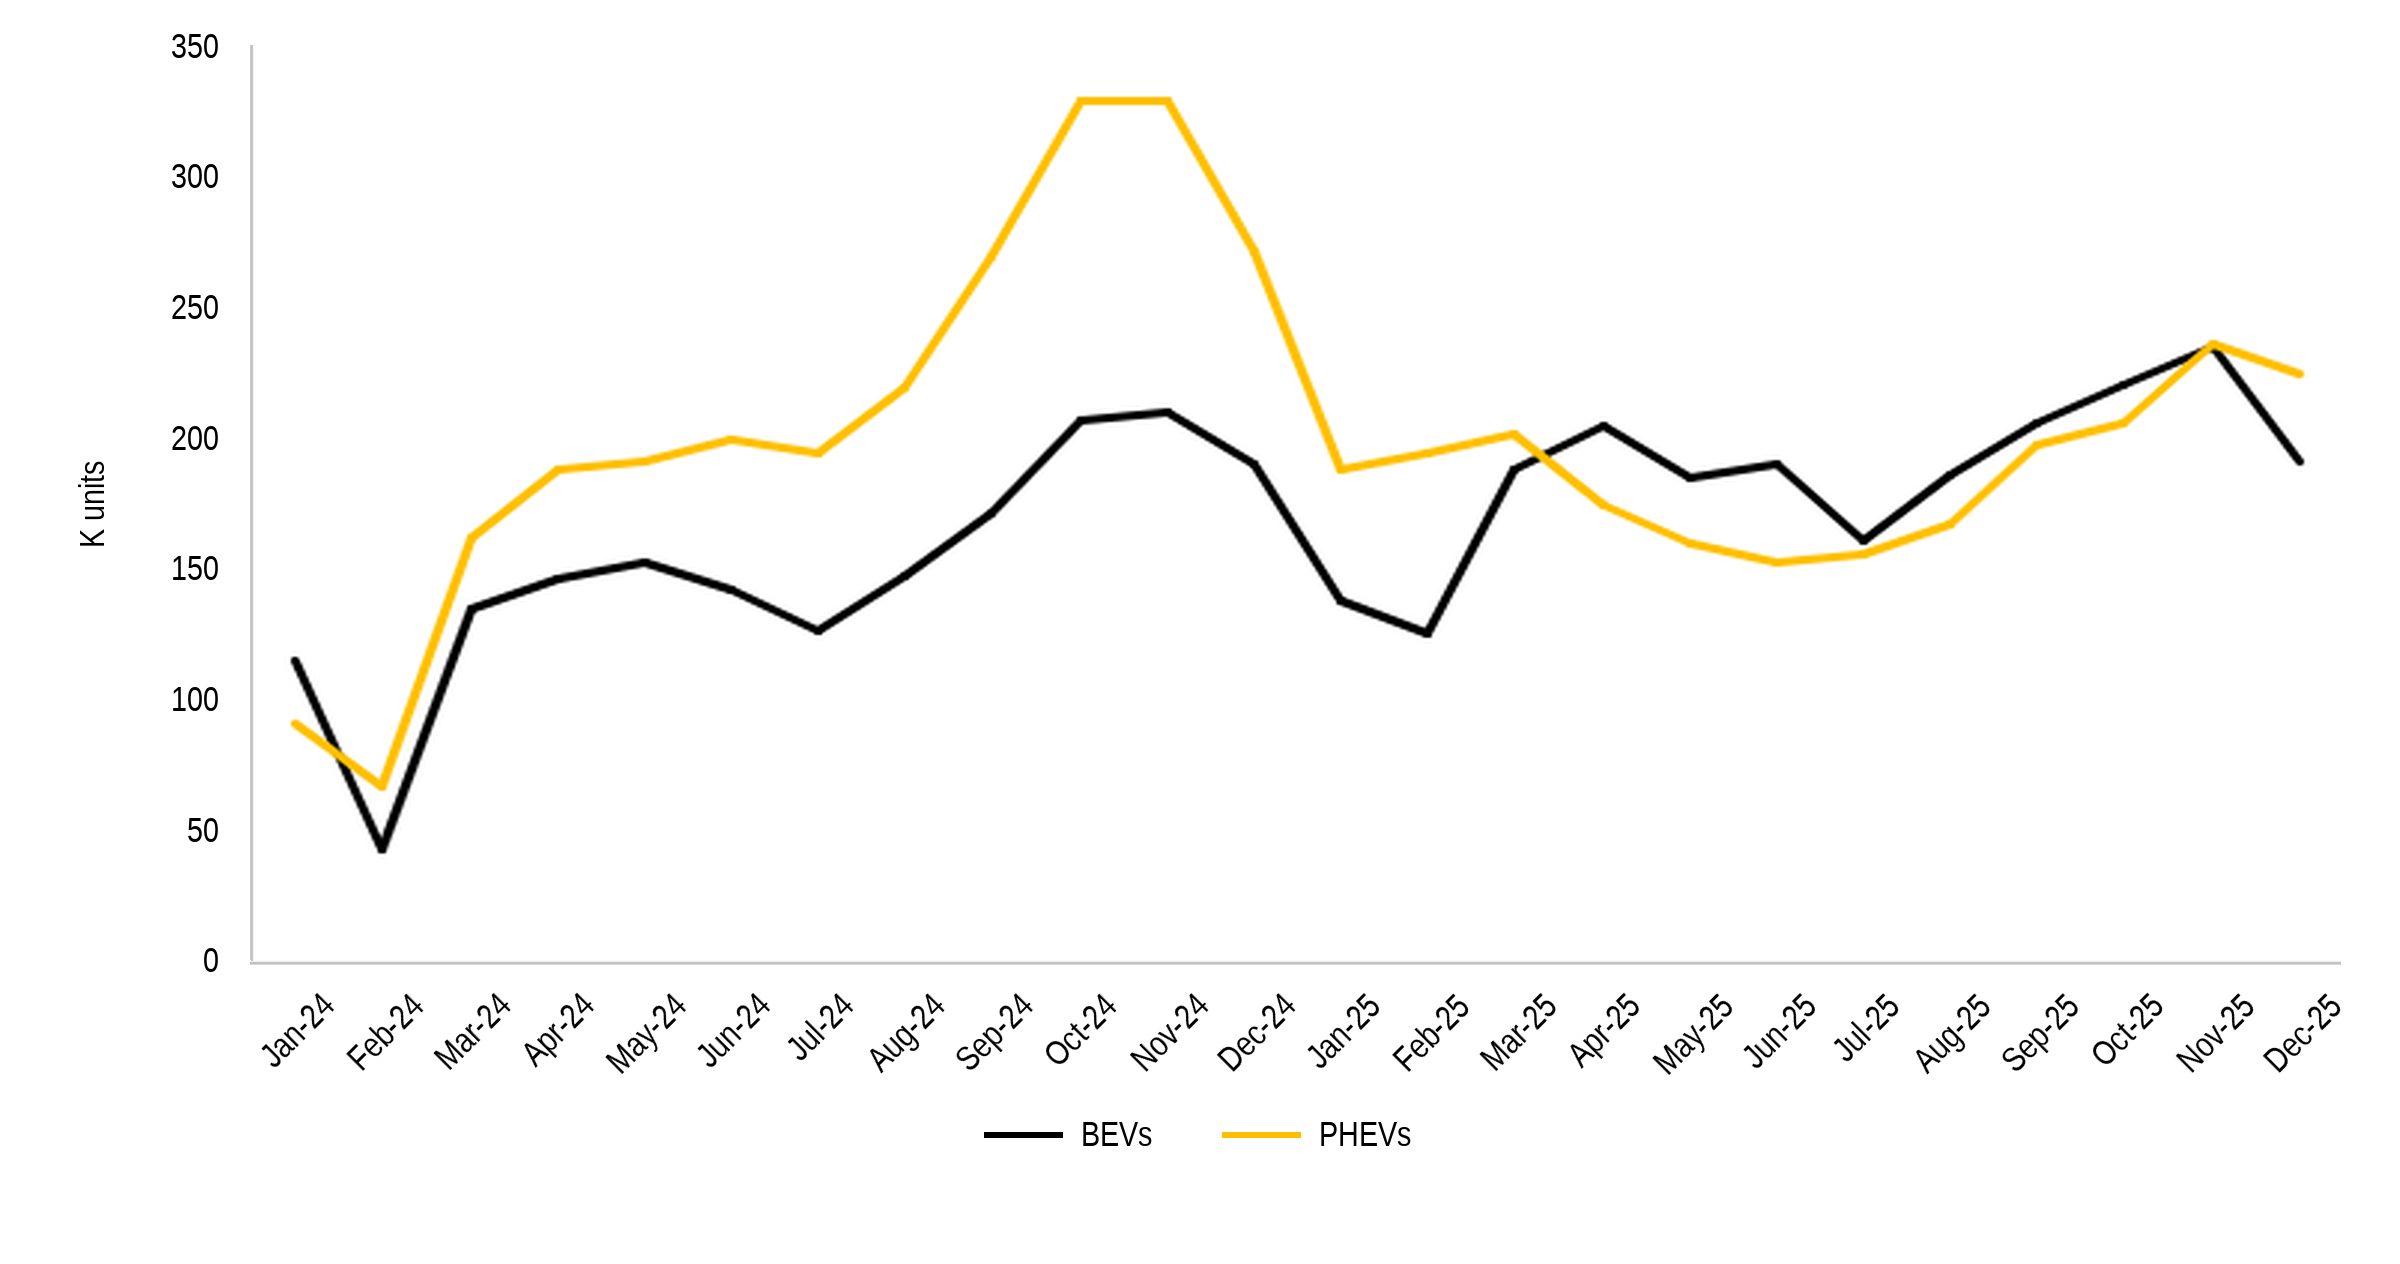
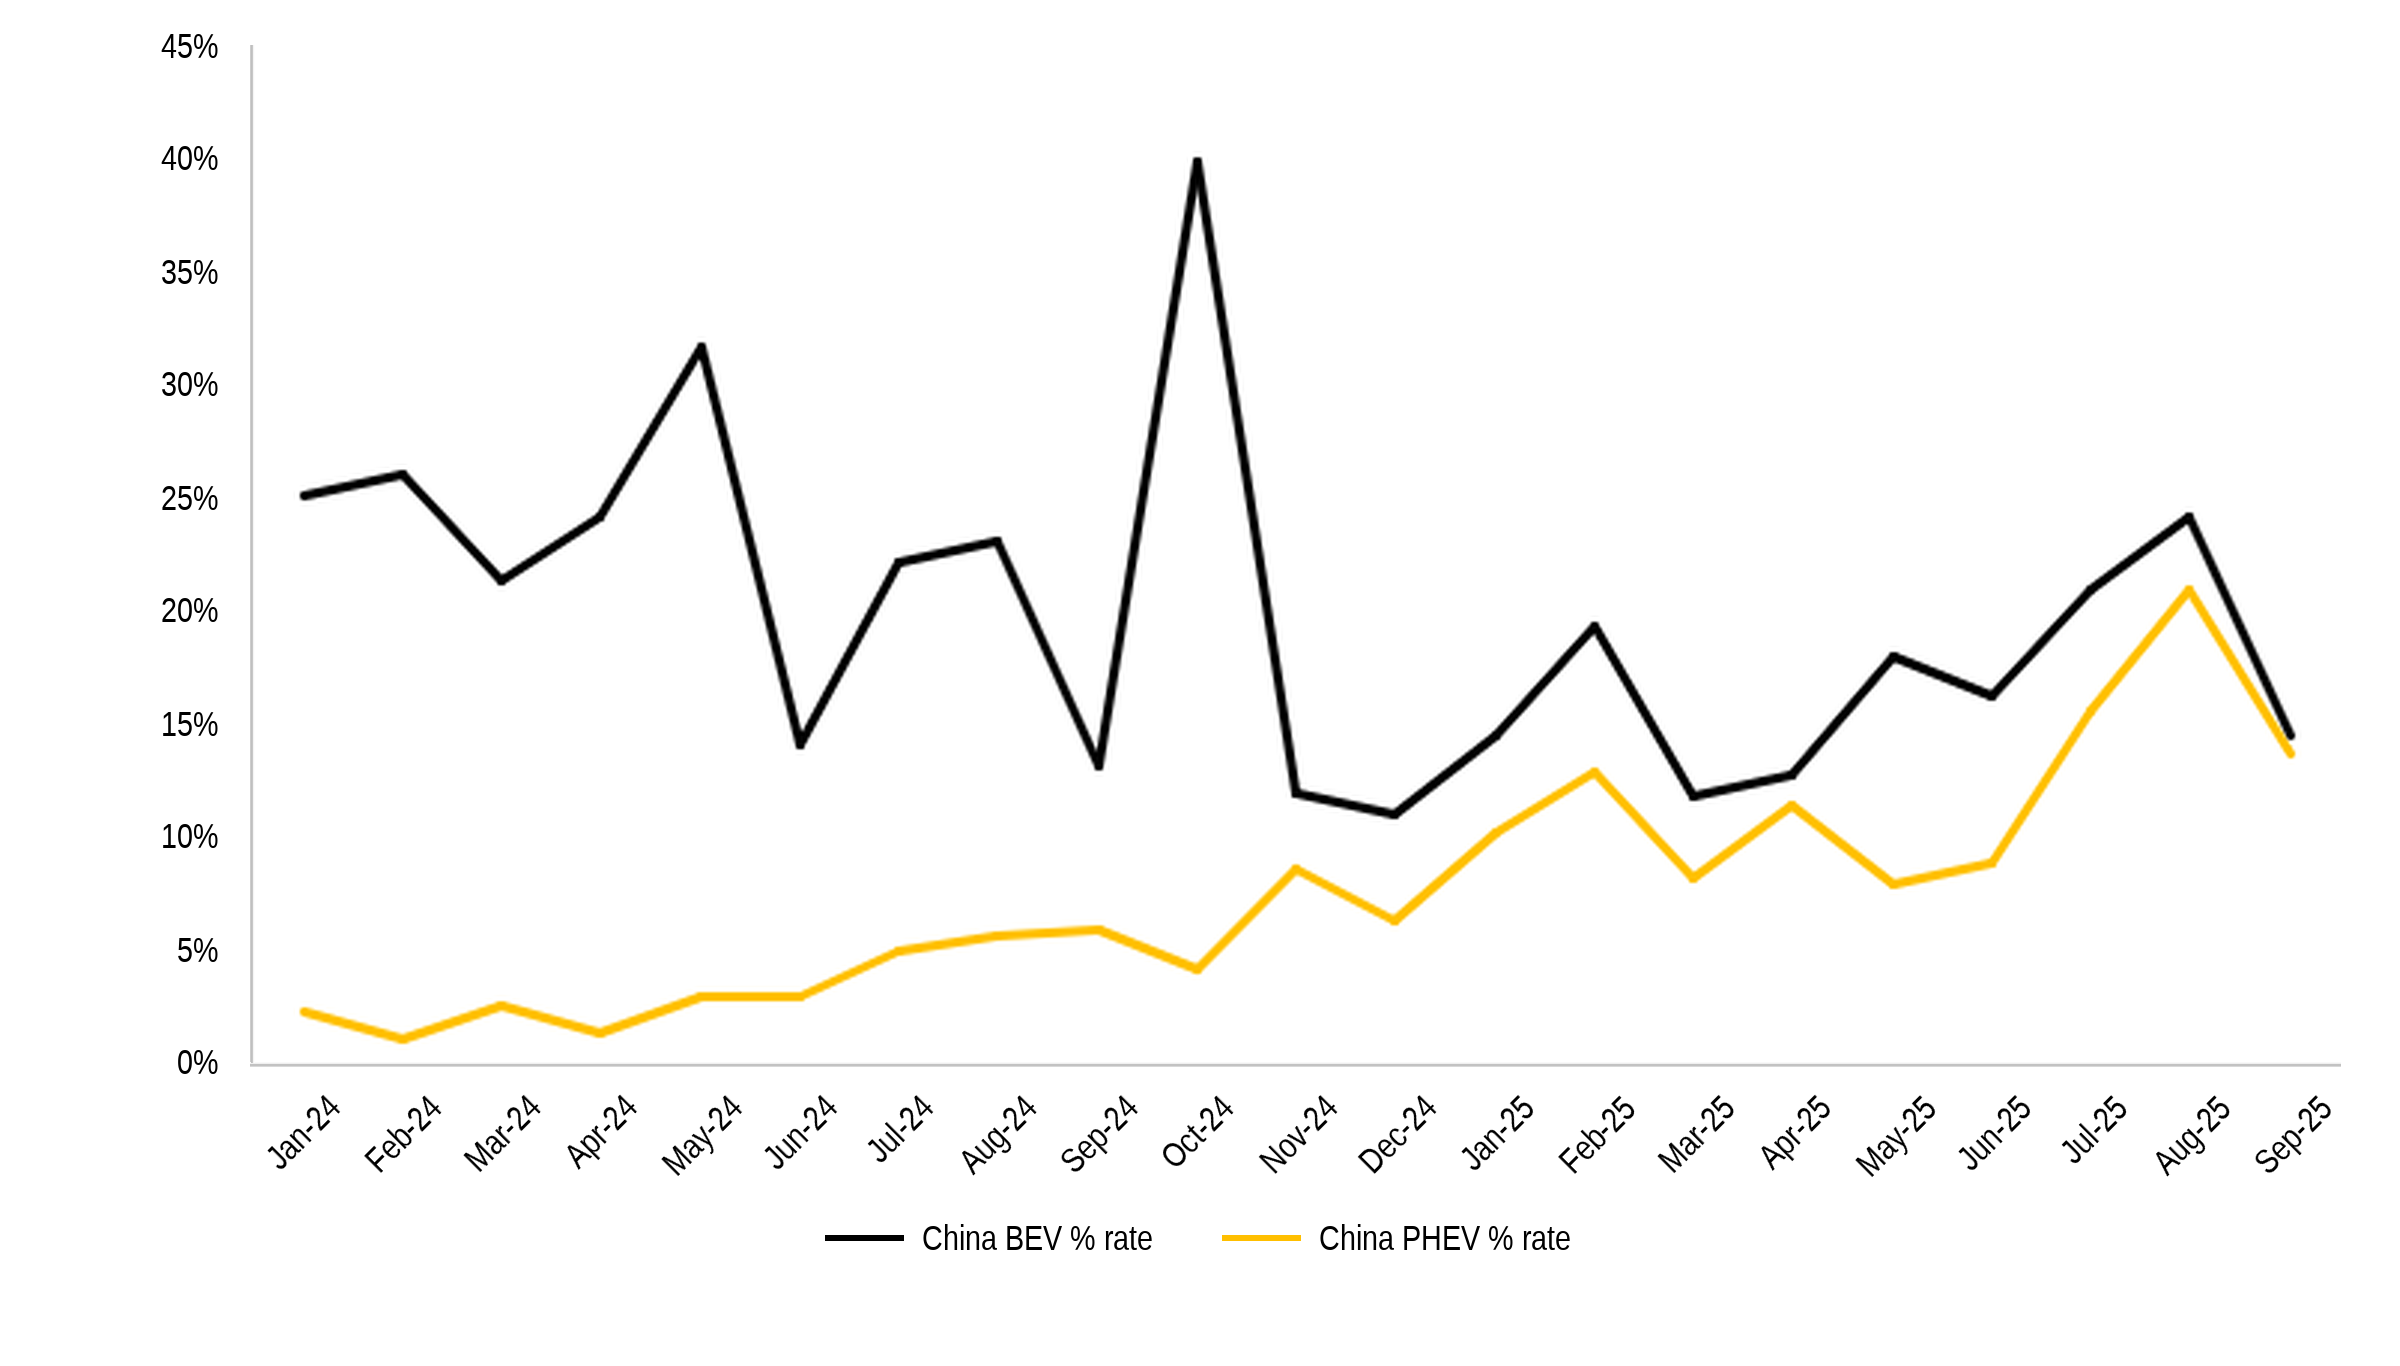
Overall, the change to minimum pricing may protect western OEMs from the most aggressive Chinese BEV competitors. But it could also retard the transition to BEVs in the “budget” end of the car market—precisely the area that been identified as underserved and most sensitive to even small changes in price. Note too that the pricing measures will not apply to PHEVs. Chinese OEMs have targeted this area of the EU market since the tariffs on BEVs were imposed (Fig.5), and this latest policy initiative will do nothing to close that loophole.
Fig. 5: EU xEV imports: Min. pricing unlikely to tackle inflow of PHEVs from China
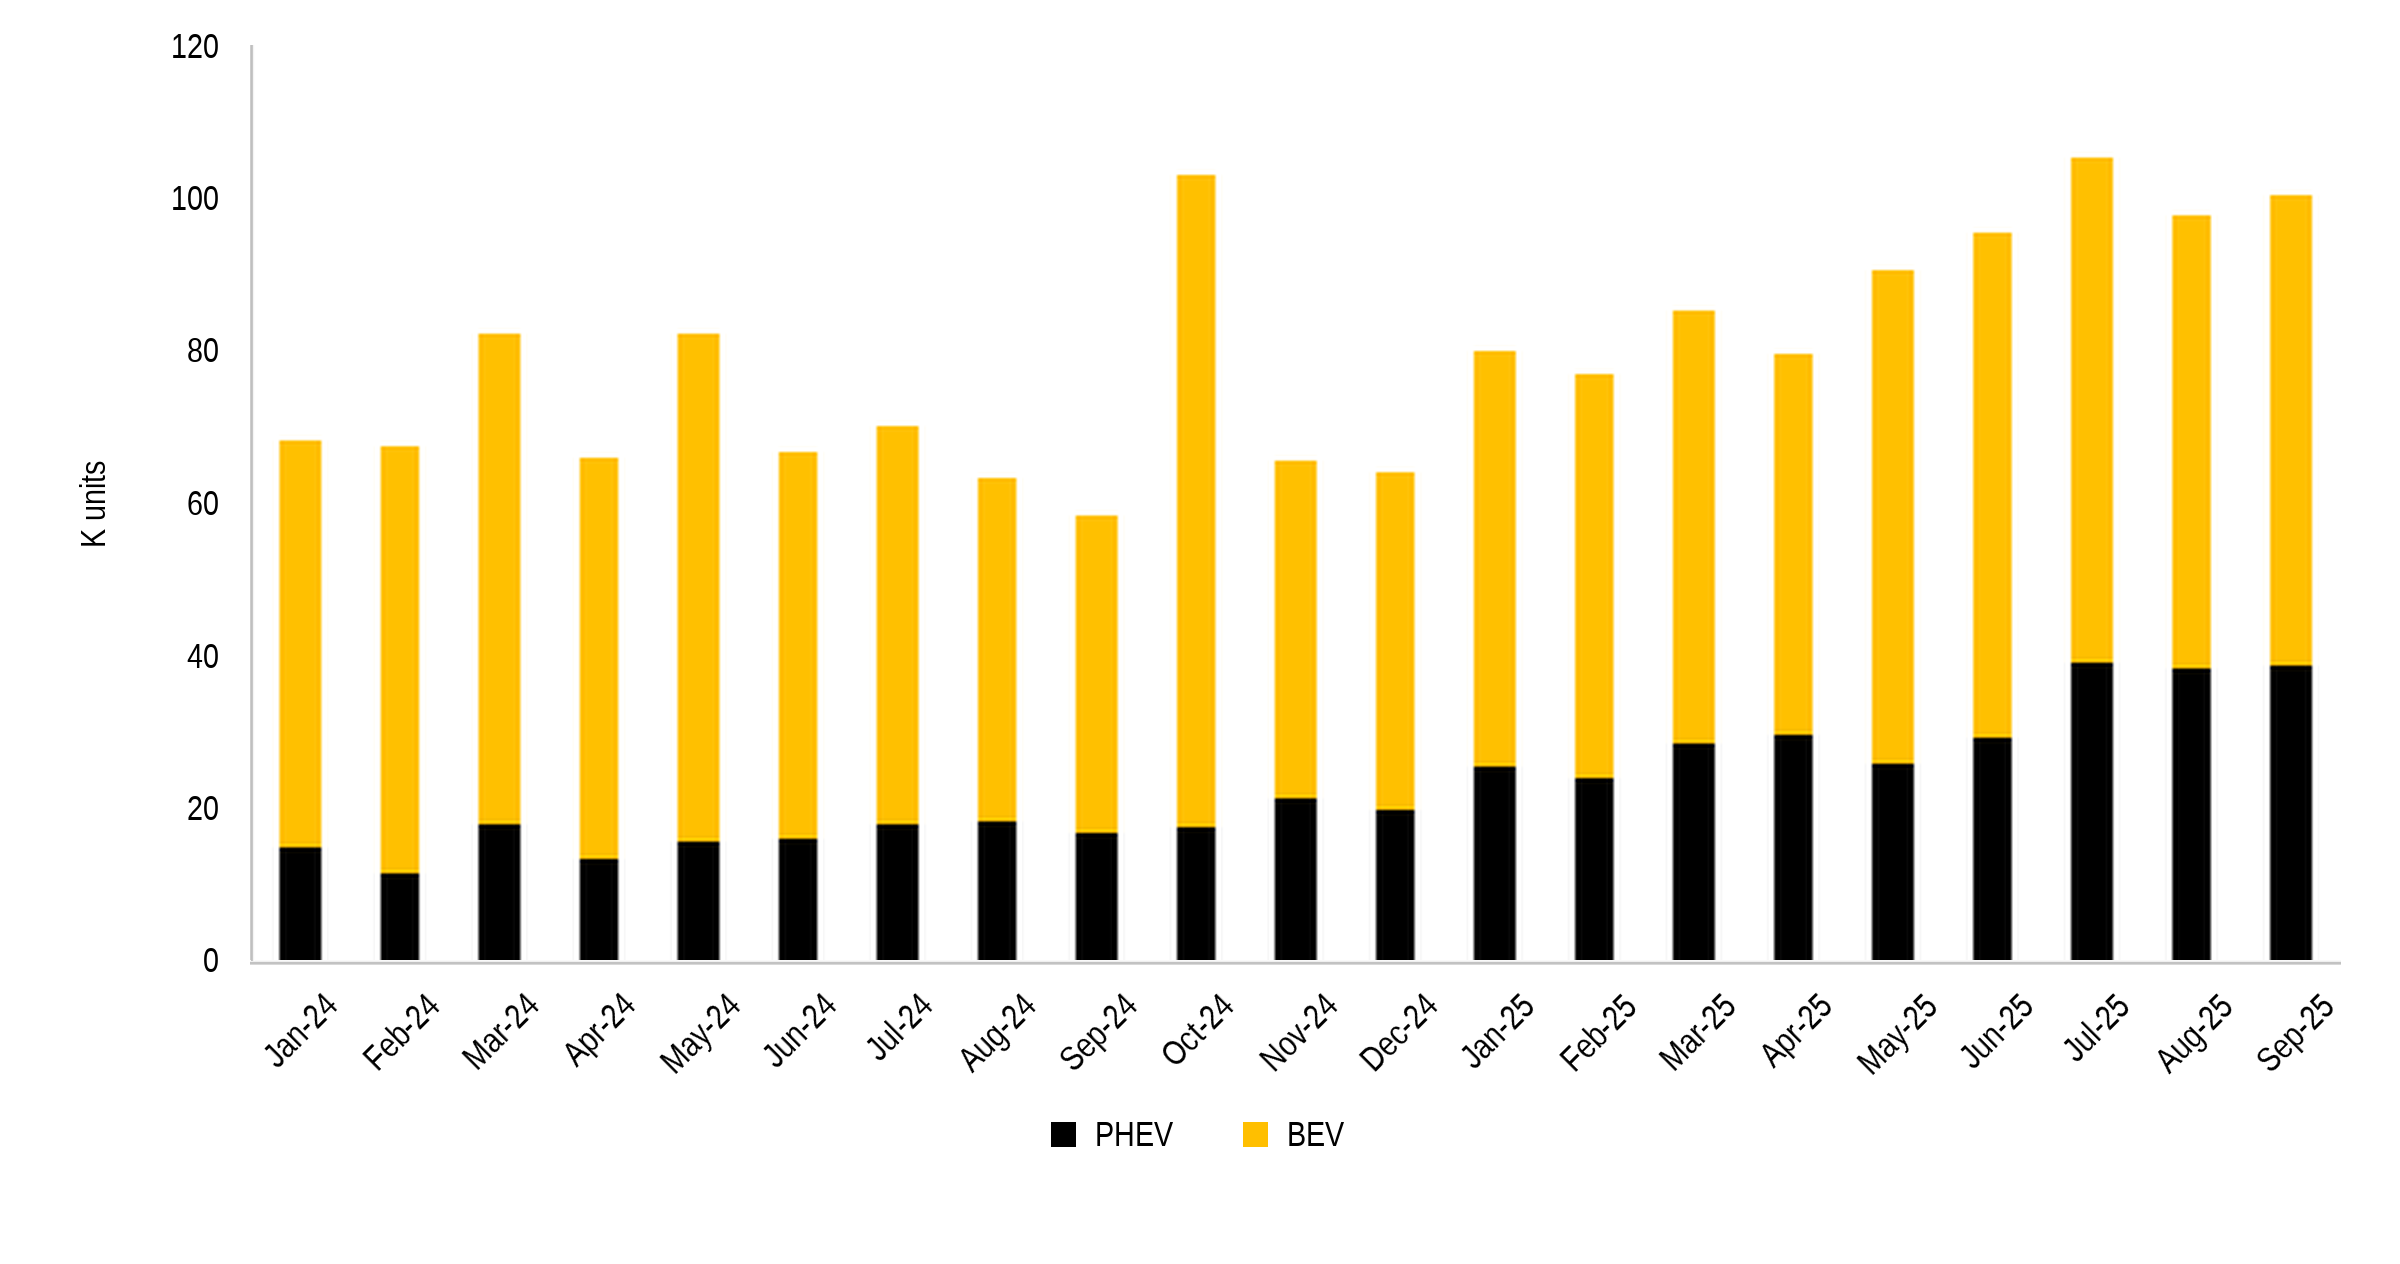
Fig. 6: China-made xEVs as a % of total EU sales for respective segment
What do both sides get from a minimum pricing agreement?
Chinese authorities were the ones that first proposed minimum pricing as a substitute for tariffs; EU authorities fleshed out the detail on how they could be implemented. Yet for both sides, the policy yields some prized outcomes. Chinese OEMs can keep more of the sales prices as margin rather than paying EU tax collectors (China carmakers’ share prices rallied on the back of the announcement). Meanwhile, those western OEMs—such as VW—with plants in China can export vehicles back to the EU without facing tariffs. In a wider sense, the move also works at the political level: China and the EU have signalled their willingness to be accommodative and avoid tension on a what is a sensitive area of industrial relations.
However, in REA’s view there are inconsistencies in the policy’s detail that could reveal themselves as obstacles to other goals in the longer term. The most important of these is the localisation of production in the EU and the transfer of technology from Chinese companies to local partners involved in EU-based joint ventures. The EU has also sought to link the setting of minimum prices to Chinese OEMs’ commitment to invest in EU plants. This kind of investment made sense to avoid tariffs and access premium EU markets. It may now be harder to justify if minimum prices boost the margins achievable on direct BEV exports from China. As a result, the EU risks undermining an important element of its policy to promote viable transition to EV production in the region.
Moreover, the introduction of minimum pricing seems likely to sit alongside other policy initiatives that appear contradictory. For example, the German government confirmed this month that it would allow Chinese brands to benefit from its €3bn subsidy programme for EVs. In contrast to similar programmes in the UK and France, Germany has imposed no requirement that a qualifying vehicle’s battery must conform to sustainability standards that tend to favour localised production. According to the country’s Environment minister, German OEMs are “confident” when it comes to competing with Chinese EV brands. With tariffs now likely to be abandoned, competition based on quality—which is where REA believes Chinese EV makers have an edge—seems set to intensify.
Fig. 7: BYD stepped up its targeting of overseas markets in late 2025
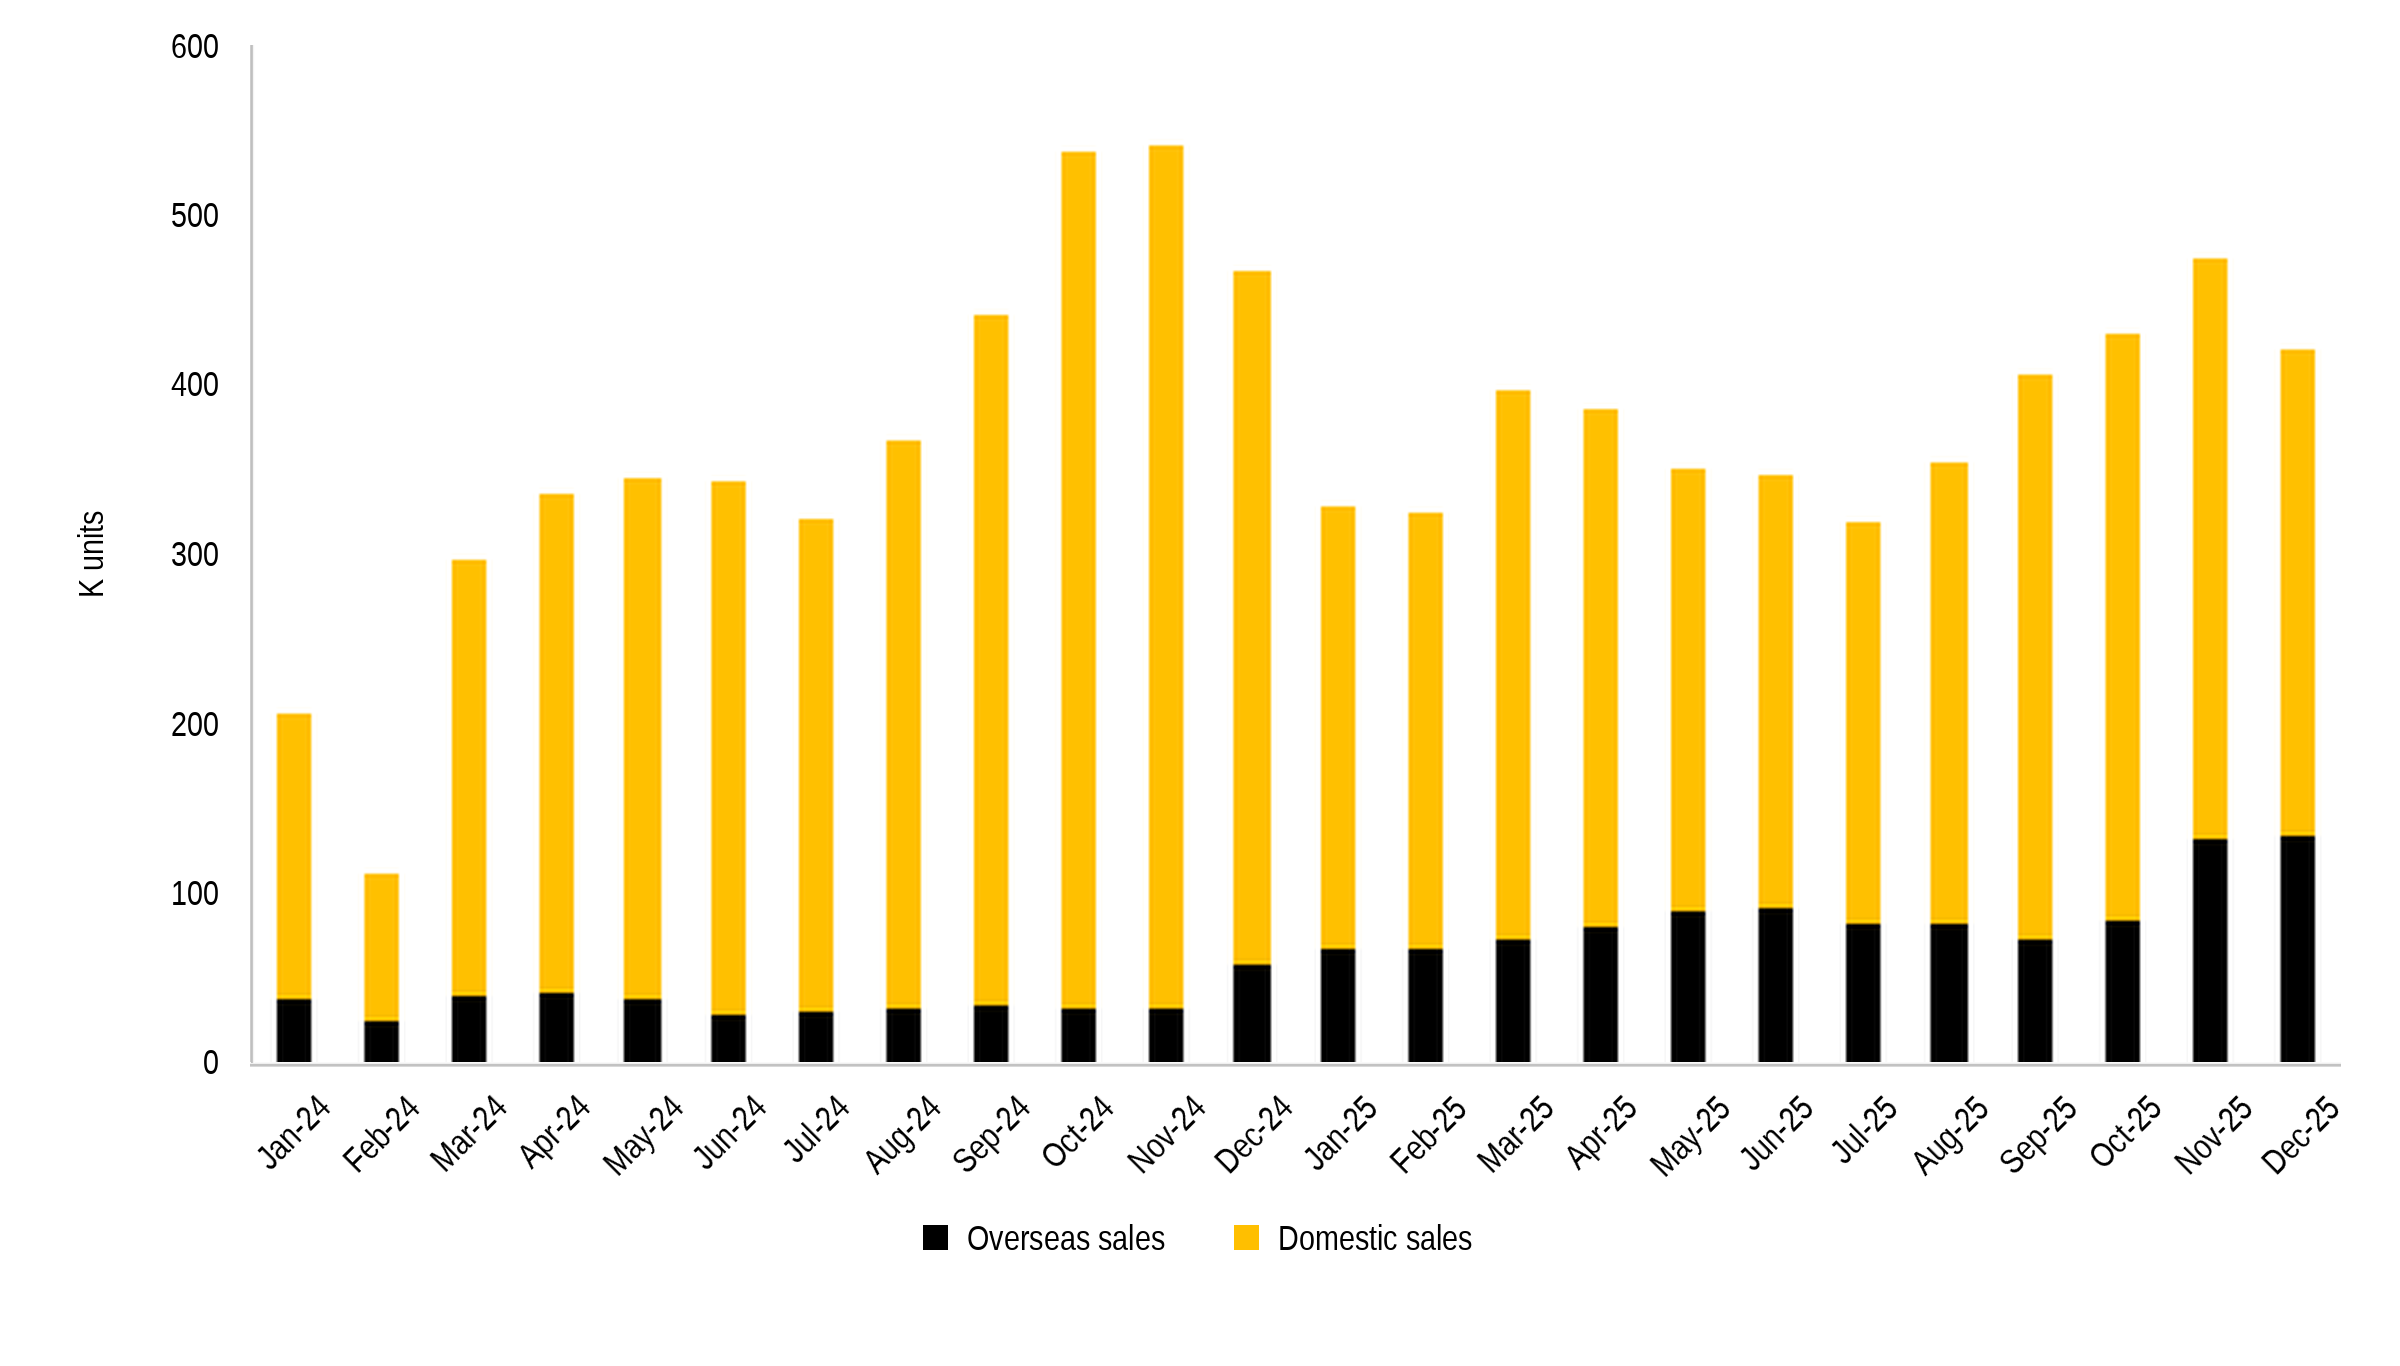
Fig. 8: BYD’s flex to PHEV sales consistent with export patterns to regions like the EU